The Importance of Financial Inclusion: How Banks Can Help Marginalized Communities
The Importance of Financial Inclusion
In an era where technology is reshaping industries, the banking sector is also undergoing significant transformation. However, one critical issue remains pressing—financial inclusion, especially for marginalized communities. As the gap in access to financial services persists, it poses a formidable barrier to economic stability and opportunity for millions. Without access to banking, individuals struggle to secure loans or savings accounts, ultimately limiting their potential for upward mobility.
When we talk about financial inclusion, we refer to the ability of individuals to access and effectively utilize financial products and services—such as bank accounts, credit, insurance, and other services essential for economic advancement. Embracing financial inclusion brings tremendous advantages, such as:
- Empowerment: Access to banking equips individuals with the tools to make informed financial decisions. For example, a family with a checking account can budget their monthly expenses more effectively rather than relying on cash transactions that may lead to overspending.
- Economic growth: When communities are empowered through financial services, they can invest in education, entrepreneurship, and home ownership. This, in turn, generates jobs and stimulates the local economy, fostering sustainable development.
- Reduced poverty: With access to savings accounts and microloans, individuals can save for emergencies, invest in their future, and ultimately improve their standard of living. A recent study highlighted that households with bank accounts save an average of 4% more compared to those without.
In the United States, the statistics regarding financial exclusion are striking. Nearly 25% of American households are either unbanked or underbanked, meaning they lack reliable access to mainstream financial services. As a result, many find themselves turning to expensive alternatives like payday loans, often accruing crippling interest rates and spiraling deeper into debt.
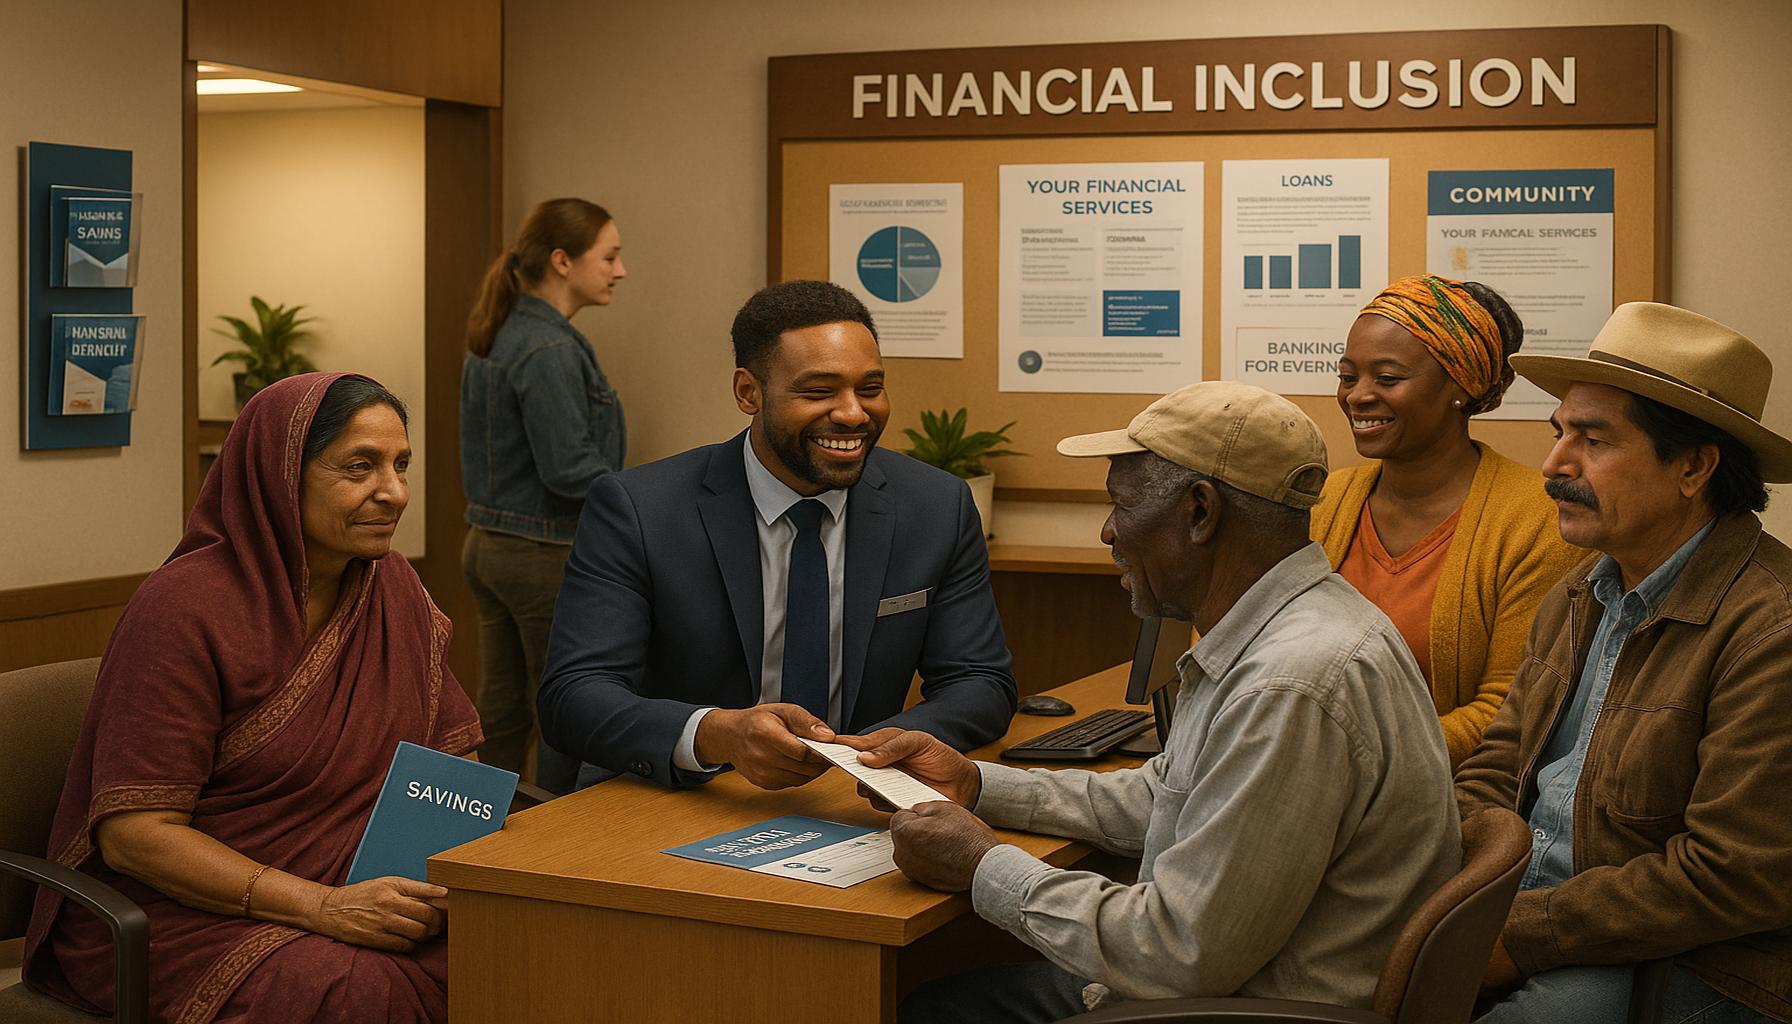
Banks, therefore, hold a pivotal role in addressing these disparities. By creating products and services tailored specifically for underserved populations, financial institutions can break down barriers to access. Initiatives such as low-fee accounts, community lending programs, and inclusive outreach efforts can foster relationships with underrepresented groups.
Education as a Cornerstone
Financial education plays a crucial role in promoting financial inclusion. Many individuals do not utilize banking services simply because they are unaware of their benefits. Banks can help by providing financial literacy workshops and resources, essential for empowering communities to take charge of their financial futures. Programs designed to teach budgeting, saving, and investment strategies can enable people to navigate the complex financial landscape effectively.
Ultimately, exploring the intersection of banking and social equity highlights the importance of fairness and accountability within the financial system. Instead of being a source of exclusion, banks can transform into catalysts for economic resilience. In an age of immense opportunity, the journey towards meaningful financial inclusion deserves unwavering investment and attention from all financial institutions committed to fostering a more equitable society.
DON’T MISS: Click here to discover effective salary negotiation strategies
Bridging the Gap: The Role of Banks in Financial Inclusion
As we delve deeper into the complexities of financial inclusion, it becomes apparent that banks possess unparalleled potential to serve as conduits for change within marginalized communities. For far too long, traditional banking systems have inadvertently perpetuated financial exclusion, leaving millions without access to basic financial services. However, the tide is beginning to turn as financial institutions recognize that creating tailored solutions not only serves the community but also benefits their bottom line.
The impact of financial inclusion reaches beyond just individuals—it touches entire communities. By providing accessible financial services, banks can enhance the overall economic landscape. Here are some key ways banks can foster inclusion:
- Product Innovation: Financial institutions can design products aimed specifically at the needs of underserved populations. Examples include low-fee checking accounts for individuals who may not meet traditional account requirements, or small business loans designed for entrepreneurs lacking formal credit histories.
- Technology Utilization: In today’s digital age, mobile banking represents a powerful tool for providing services to remote areas. By leveraging technology, banks can reach clientele without traditional branch locations, ensuring that rural or low-income populations have access to vital financial resources.
- Partnerships with Community Organizations: Collaborating with local agencies and non-profits allows banks to effectively address the unique barriers faced by marginalized groups. Such partnerships can facilitate outreach and education, helping to build trust and ultimately leading to increased financial literacy.
Statistics underscore the necessity of such initiatives. A report from the Federal Reserve indicated that nearly 13% of Black households and approximately 14% of Hispanic households are unbanked, compared to just 3% of white households. Moreover, the disparity in credit access is even more pronounced. Many individuals from marginalized backgrounds face systemic barriers that hinder their ability to secure loans or credit, creating a cycle of exclusion that can be difficult to escape. This situation serves as a stark reminder that tailored financial products can pave the way towards greater equity, allowing diverse populations to accumulate wealth and build stability.
Furthermore, banks can harness the potential of social media and community events to spread awareness of financial services. Many young people and low-income individuals turn to social platforms for information, making these channels valuable for outreach and engagement. By creating informative content that demystifies banking processes, financial institutions can attract a wider audience and guide individuals toward making informed financial choices.
A Call to Action
As the conversation around financial inclusion grows, so too must the commitment of banks to foster an inclusive environment. Institutions that prioritize serving marginalized communities not only align themselves with ethical practices but also position themselves as leaders in an evolving market. With the right blend of innovation, outreach, and education, banks can redefine their role and become champions for financial inclusion, transforming lives and communities for generations to come.
DISCOVER MORE: Click here to learn how to apply easily
Empowering Communities Through Financial Literacy
While access to financial products is crucial, the significance of financial literacy cannot be overstated. Many individuals in marginalized communities face barriers not only in accessing bank accounts but also in understanding the financial tools available to them. Banks have a unique opportunity to bridge this knowledge gap by providing educational programs tailored to these populations. Research from the National Endowment for Financial Education demonstrates that financial literacy is strongly correlated with improved financial decision-making and overall economic stability.
Financial institutions can implement workshops and webinars aimed at demystifying banking processes, teaching concepts like savings, credit building, and responsible borrowing. For instance, programs delivered in collaboration with local schools can reach young people early, instilling good financial habits from a young age. Furthermore, tailored workshops that address cultural contexts and community-specific challenges will resonate more with participants and increase engagement.
Moreover, banks might consider the implementation of financial coaching programs that offer individualized support. Trained coaches can work directly with community members to create personalized financial plans that reflect their unique needs and goals. This personalized approach is especially important for individuals recovering from economic hardships or navigating financial setbacks, offering them not just knowledge but also a supportive hand to guide them through the process of rebuilding their financial health.
Creating Economic Opportunities Through Investment
Banks also play a critical role in creating economic opportunities by investing in local businesses within marginalized communities. This can take many forms, including offering microloans to entrepreneurs who may not qualify for traditional financing. By providing easier access to capital, banks can stimulate local economies, fostering entrepreneurship and creating jobs within the community. A 2019 study from the Aspen Institute found that businesses owned by individuals from underserved demographics not only enhance economic resilience but also boost overall community strength.
In addition, establishing community development financial institutions (CDFIs) can further enhance this investment. CDFIs focus on providing financial services in low-income communities and can serve as a crucial link between banks and the individuals looking to uplift their economic status. By supporting the growth of CDFIs, banks can contribute to a more equitable financial system that prioritizes community investment and development.
A significant aspect of these opportunities revolves around the promotion of credit unions. Credit unions, being member-owned, often provide more accessible rates and services tailored for those in the community. Banks can partner with these institutions to bolster their impact, allowing greater outreach and empowerment of individuals who might otherwise see themselves as outside the traditional banking system.
All these initiatives highlight the unwavering importance of community engagement. Active participation from local residents in the development and implementation of financial products ensures that the services provided actually meet their needs, creating a sense of ownership and trust. Trust is essential, especially in communities where historical marginalization has bred skepticism towards financial institutions. By prioritizing transparency and ethical engagement practices, banks can transform skepticism into partnership.
DON’T MISS: Click here to discover essential financial strategies
Conclusion
The journey towards financial inclusion is not just a buzzword; it is a critical pathway for fostering economic stability and resilience in marginalized communities. Banks hold a pivotal role in transforming lives by not only providing access to financial services but also equipping individuals with the knowledge and resources they need to navigate their financial futures successfully. Initiatives that prioritize financial literacy and tailored community engagement lay the groundwork for empowering residents to break free from cycles of poverty and distrust.
Moreover, investments in local businesses through microloans and support for community development financial institutions can serve as catalysts for entrepreneurship and job creation. Such strategies not only enhance economic prospects but also strengthen the social fabric of these communities. By investing where it counts, banks can contribute to a more equitable financial landscape that fosters hope and opportunity.
As we move forward, it is imperative for financial institutions to consider their **local** context and the particular needs of the communities they serve. Building trust through transparent practices and ethical engagement will be fundamental in overcoming historical skepticism towards banking systems. The collaboration between banks, local organizations, and residents can bridge existing gaps, ensuring that financial services are not just accessible, but also relevant and impactful.
Ultimately, the road to financial inclusion is an ongoing effort that requires commitment from all stakeholders. By prioritizing the empowerment of marginalized communities, we can pave the way for a future where everyone has the opportunity to thrive financially, positively impacting society as a whole.