How Financial Planning Can Evolve at Every Stage of Life
Understanding Financial Planning Through Life Stages
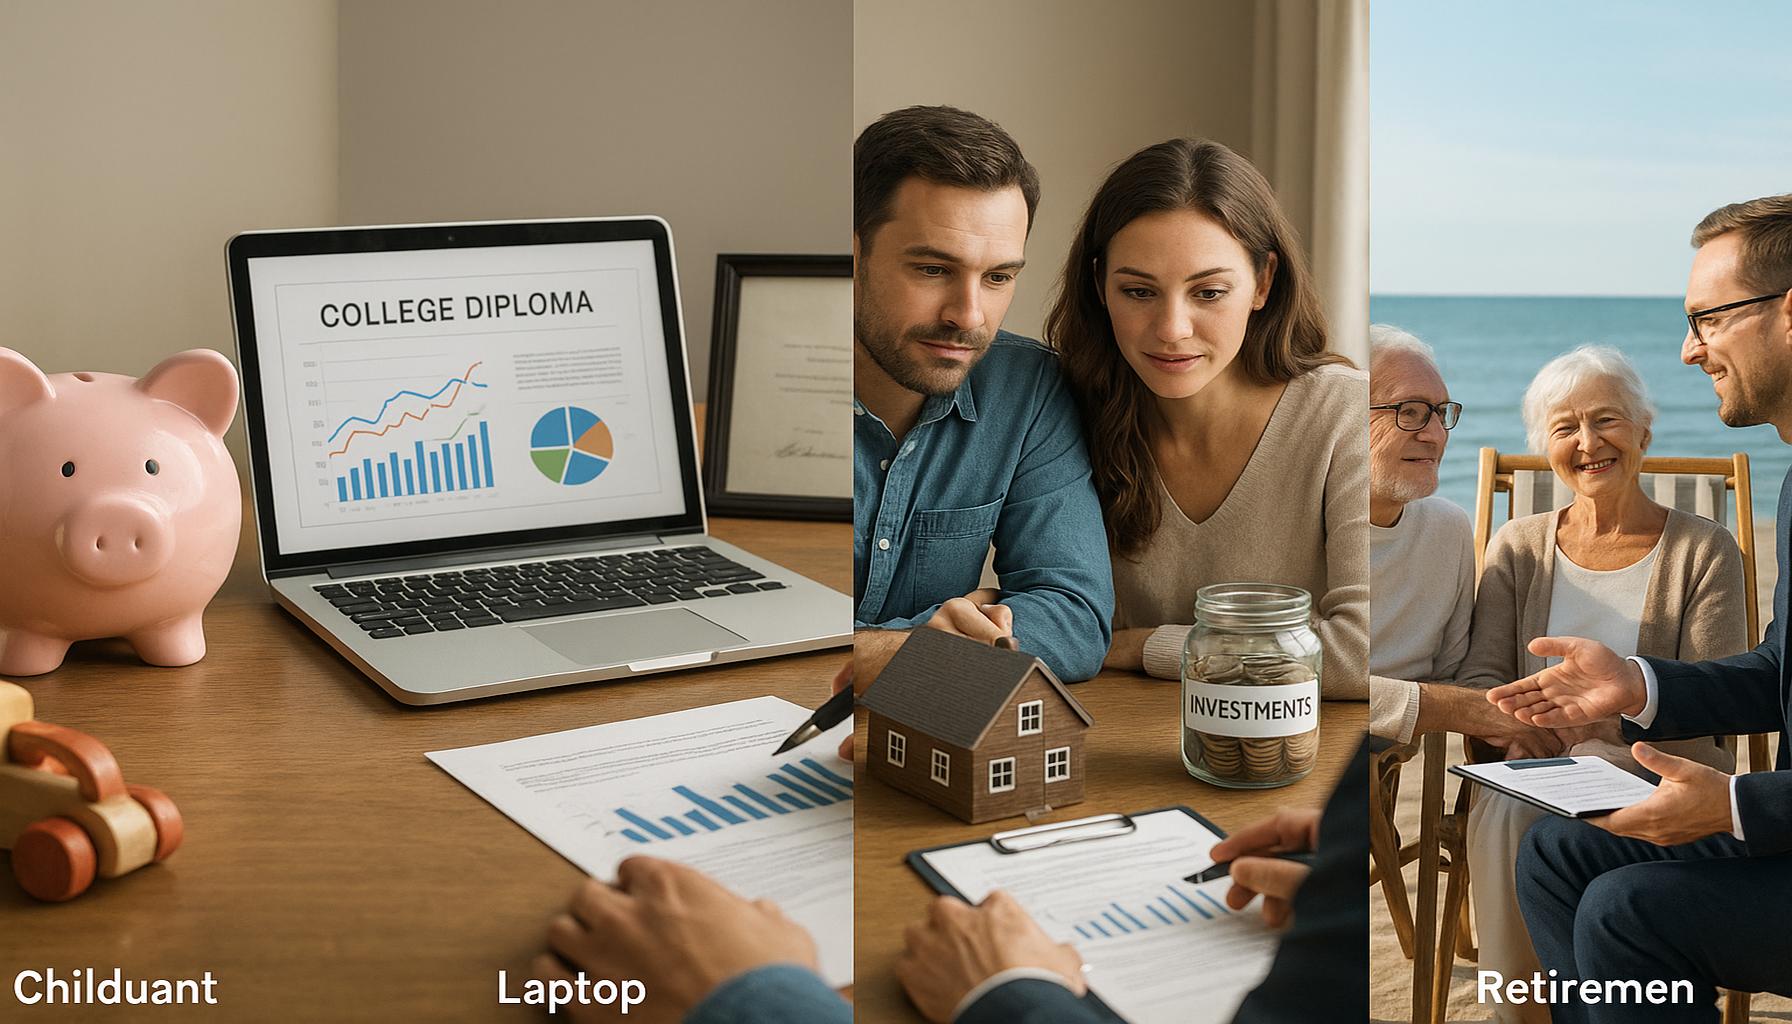
Life is a journey marked by various stages, each with its own financial landscape. As individuals advance from one phase to another, their financial objectives, strategies, and considerations evolve. Understanding these changes is crucial for effective financial planning that aligns with personal goals and life transitions.
Each life stage presents distinctive financial demands. Consider the following phases:
- Young Adults: This stage often involves entering the workforce, which is a time filled with excitement and uncertainty. Many young adults are beginning to earn their own income while simultaneously managing student loan debt. They may also be considering significant purchases, such as a new car or their first home. Crafting a solid budget that addresses student loans, living expenses, and savings for emergencies is key. Utilizing financial tools like budgeting apps can help track expenditures and encourage responsible spending habits.
- Families: As individuals settle down, their financial landscape becomes more complex. The focus often shifts to balancing housing costs, education expenses for children, and long-term savings. Parents may need to consider purchasing life insurance or a larger home, necessitating increased financial management. Educational savings accounts, such as 529 plans, can also play a crucial role in preparing for future college expenses, making it essential to outline these goals early on.
- Midlife: During this crucial phase, individuals typically prioritize retirement savings. This often involves maximizing contributions to retirement accounts like 401(k)s or IRAs. Additionally, many adults face the emotional and financial responsibilities of caring for aging parents, which can strain finances. Considering long-term care insurance and establishing estate plans becomes pivotal in ensuring that both personal financial stability and family responsibilities are managed effectively.
- Retirement: This stage demands careful management of resources accumulated over a lifetime. Understanding how to sustainably withdraw from retirement accounts without depleting funds too quickly is vital. Moreover, healthcare costs can become a significant concern, necessitating planning for insurance and out-of-pocket expenses. Estate planning, including wills and trusts, is also essential to ensure one’s legacy is preserved and passed on according to personal wishes.
Effective financial planning throughout these stages not only safeguards financial health but also offers peace of mind. By acknowledging that financial strategies need to shift alongside individual life changes, individuals can make informed decisions that enhance their overall financial well-being. Embracing a dynamic approach encourages adaptability, ensuring that financial goals align with current circumstances and aspirations.
In conclusion, understanding financial planning as it correlates with life’s transitions can significantly impact one’s overall experience. Armed with the right knowledge, individuals can navigate their financial paths with confidence and clarity, opening doors to better opportunities and improved quality of life.
DISCOVER MORE: Click here to learn how to manage your budget effectively
Financial Foundations for Young Adults
As young adults embark on their professional lives, they often find themselves at a crossroads of opportunities and challenges. This vibrant phase is characterized by newfound independence, which brings the excitement of earning a salary for the first time. However, with this freedom also comes the weight of financial obligations, including student loan debt, housing costs, and day-to-day living expenses. Establishing a strong financial foundation is essential for setting the stage for future success.
During this period, developing a comprehensive financial plan should focus on the following key areas:
- Budgeting: Creating a detailed budget allows young adults to track their income and expenses, making it easier to allocate funds for essentials like rent, groceries, and utilities. Utilizing financial apps can streamline this process, helping individuals monitor their spending habits and adhere to their budgets.
- Debt Management: Young adults often grapple with student loan debt, making it imperative to devise a repayment strategy. Understanding different repayment options, including income-driven plans or refinancing, can alleviate financial strain and promote faster debt reduction.
- Savings Strategy: Building an emergency fund should be a top priority to cover unexpected expenses such as medical bills or car repairs. Financial experts recommend saving at least three to six months’ worth of living expenses, providing a cushion against unforeseen financial setbacks.
- Investment Awareness: Beginning to invest early, even with small contributions, can yield significant long-term benefits. Exploring low-cost index funds or employer-sponsored retirement accounts offers opportunities for growth while instilling the importance of preparing for future financial stability.
As young adults navigate this critical stage, they also face societal pressures that impact their financial decisions. The urgency to buy a new car, live in trendy neighborhoods, or travel can lead to hasty spending choices that may hinder long-term goals. Recognizing the importance of prioritizing financial health over immediate gratification is vital for building a secure future.
Navigating Family Dynamics and Finances
Once individuals transition into family life, the financial landscape becomes considerably more complex. The responsibilities of providing for a partner and children introduce new challenges that require a holistic approach to financial planning. This phase necessitates evaluating existing financial strategies and adapting them to accommodate family growth and associated costs.
Key considerations for families looking to strengthen their financial situation include:
- Insurance Policies: As families grow, so does the need for insurance. Life insurance becomes essential for protecting loved ones in case of unforeseen circumstances. Parents should also consider health, dental, and disability insurance to safeguard their family’s well-being.
- Education Savings: Planning for a child’s education requires a proactive approach. Establishing 529 plans or other educational savings accounts early on can help alleviate the financial burden of rising tuition costs, enabling families to contribute towards an inevitable climb in higher education expenses.
- Long-Term Financial Goals: Families should focus on long-term financial objectives, such as purchasing a larger home or investing in retirement. Crafting a comprehensive financial plan that integrates these goals while managing daily expenses is essential for financial security.
In this evolving financial landscape, understanding the nuanced changes in family dynamics is crucial. As new priorities arise, adapting financial strategies will ensure families remain on track to achieve their goals while maintaining a healthy balance between current needs and future aspirations.
DISCOVER MORE: Click here for handy finance apps
Retirement Planning: A Focus on Legacy
As individuals reach mid-life, the focus of financial planning typically shifts toward not only preparing for retirement but also ensuring a stable financial legacy for the next generation. This transformative period encourages a reevaluation of financial goals and necessitates deliberate strategies for sustainability and wealth accumulation.
Mid-life financial planning encompasses several critical components:
- Retirement Contributions: By mid-life, the accumulation of retirement savings becomes paramount. Individuals should aim to maximize contributions to employer-sponsored 401(k) plans, particularly if employer matches are available, as this free money significantly bolsters retirement funds. Additionally, exploring various retirement account options, such as Traditional or Roth IRAs, can offer tax advantages that benefit long-term savings.
- Investment Diversification: As the retirement date draws closer, refining one’s investment strategy is crucial. Diversifying a portfolio can mitigate risk and enhance growth potential. Investors should consider adjusting their asset allocation—gradually shifting from aggressive investments to more conservative options that protect capital while still allowing for growth.
- Estate Planning: During this phase, drafting a comprehensive estate plan helps ensure that assets are distributed according to one’s wishes. Creating wills, establishing trusts, and designating beneficiaries are essential steps that protect both financial interests and family legacies. Additionally, discussing these plans with family members fosters clarity and reduces potential conflict.
- Health Care and Long-Term Care Needs: Acknowledging the realities of aging includes planning for health care costs, which can be substantial as individuals retire. Evaluating health insurance options, including Medicare and long-term care insurance, ensures that individuals and their families are prepared to manage potential medical expenses.
One undeniable reality is that financial literacy becomes increasingly important as individuals approach retirement. As life expectancies rise, the gap between savings and potential living expenses widens. Empowering oneself with knowledge about retirement vehicles, market trends, and economic shifts can greatly influence the sustainability of financial resources throughout retirement.
Aging Gracefully: Financial Planning for Retirement Living
Upon entering retirement, many individuals confront a new phase of financial planning that emphasizes lifestyle choices, health considerations, and sustainable wealth management. This stage is about more than just finances; it’s an opportunity to enjoy the fruits of years of labor while also passing knowledge to those who follow.
Retirees should consider the following financial strategies to navigate this new chapter:
- Budgeting for Retirement: Creating a new budget that reflects a potentially reduced income stream is crucial in this phase. Understanding fixed versus discretionary expenses helps retirees allocate their resources effectively, allowing for a fulfilling lifestyle without jeopardizing financial security.
- Withdrawal Strategy: Developing a systematic withdrawal plan from retirement accounts ensures that retirees avoid depleting their savings too quickly. Financial advisors typically recommend withdrawing 4% annually, but individual circumstances can necessitate tailored strategies that account for market conditions and personal expenses.
- Social Security Optimization: Timing when to begin drawing Social Security benefits can have profound impacts on overall retirement income. Retirees should evaluate when to claim benefits, as delaying this can lead to increased monthly payments, providing a more substantial financial cushion later in life.
- Philanthropic Endeavors: Many retirees find joy in charity and giving back to their communities. Planning for charitable contributions not only allows individuals to leave a lasting legacy but can also provide tax benefits. Establishing donor-advised funds or charitable trusts can help facilitate these desires while managing taxes effectively.
Each transitional stage of life—from young adult to retiree—offers unique challenges and opportunities for financial planning. Understanding how to navigate these phases thoughtfully can foster not only financial security but also a legacy of wisdom for future generations to build upon.
LEARN MORE: Click here to discover how chargebacks work
Embracing Change: The Journey of Financial Planning
In a world where financial landscapes are constantly shifting, understanding how financial planning evolves at every life stage becomes essential for achieving long-term well-being and security. From navigating the complexities of young adulthood to undertaking the responsibilities of mid-life and finally embracing the rewards of retirement, each phase presents distinct opportunities and challenges that require thoughtful strategies.
The importance of proactive financial planning cannot be overstated. As individuals transition through life stages, they must adapt their financial goals to align with changing circumstances—be it managing student loans, saving for children’s education, or planning for healthcare in retirement. Equipping oneself with knowledge about available resources, investments, and tax implications will empower individuals to make informed decisions that not only secure their futures but also enhance their quality of life.
Moreover, as we journey through life, fostering conversations about financial literacy can reinforce a culture of awareness and preparedness among family members, ensuring that knowledge is passed down the generations. Engaging with financial advisors, setting clear goals, and revisiting plans periodically serve as foundational practices that help navigate this intricate process.
Ultimately, effective financial planning is a lifelong endeavor that evolves in tandem with personal growth and life experiences. By embracing flexibility and being open to change, individuals can cultivate not just a sustainable financial legacy but also a path that inspires others to do the same. The choices made today can resonate far beyond one’s lifetime, setting the stage for future generations to thrive.